A carefully curated perspective for our clients and neighbors across Chicagoland.
When you start looking for a home, you will hear both words very quickly. They are related, but they are not the same, and knowing the difference helps you plan.
Pre-qualified: a first estimate
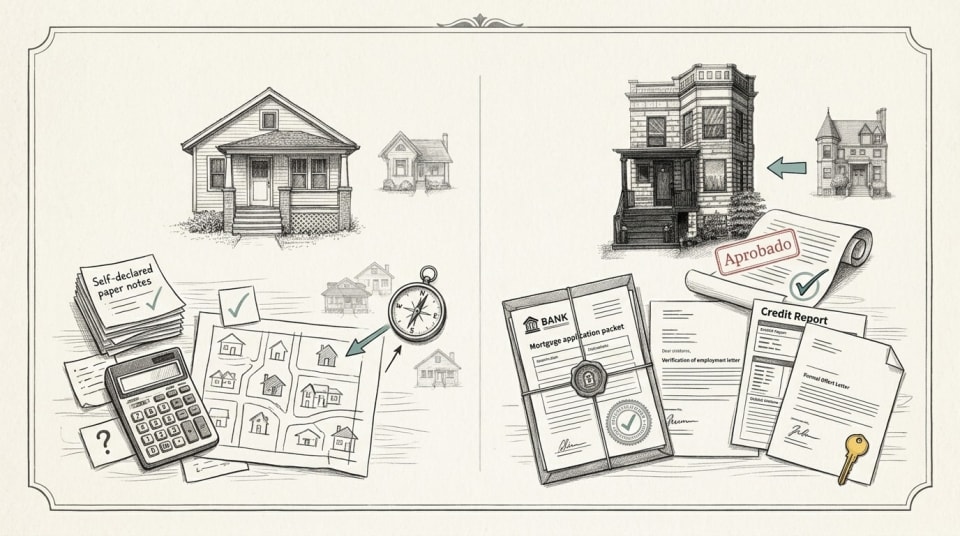
Pre-qualification is usually a quick conversation or form. You share basic information about your income, debts and savings, and the lender gives you a general idea of what you might be able to borrow. It is a useful starting point, but it is based on what you tell the lender, not on checked documents.
Pre-approved: a deeper review
For a pre-approval, the lender reviews documents such as proof of income, bank statements and your credit history. The result is a more reliable picture of the loan amount you could be approved for, and it usually comes as a letter you can share with a seller.
Why it matters when you make an offer
Sellers want to know that a buyer can actually finish the purchase. An offer that comes with a pre-approval letter is generally taken more seriously than one without it. It also saves you time, because you search within a realistic range from the start.
What to keep in mind
- A pre-approval is not a final loan approval. The home must still be appraised and your finances are checked again before closing.
- Avoid opening new credit accounts or making large purchases while your loan is in process.
- Ask the lender how long the pre-approval stays valid.
- Compare more than one lender, and ask each to explain the costs in plain terms.
If you are not there yet
Not qualifying today does not mean never. A good lender will tell you what to improve and give you a plan, whether that is paying down a debt, saving a bit more or building credit history over time. Having that plan early is one of the most useful things you can do.